


The Bitcoin Newsletter 40
Welcome to the 40th Edition of The Bitcoin Newsletter
Before getting into this week’s newsletter, my thoughts are with everyone affected by the recent Coldcard incident. It is devastating to hear about people losing bitcoin through a product specifically designed to make self-custody safer.
The incident raises a broader question that every Bitcoiner should think seriously about: How do we self-custody properly without creating additional layers of complexity and trust? I do not want to make specific recommendations here, but one lesson is worth keeping in mind: Bitcoin itself is already extraordinarily robust.
We should be careful not to place blind trust in additional hardware or systems simply because they are marketed as providing greater security. In many cases, simplicity matters.
This month, I continue with Part II of Inflation and the Illusion of Wealth.
In Part I, I examined how monetary inflation creates the appearance of prosperity, distorts price signals, concentrates wealth, and follows a recurring historical pattern of monetary debasement. I ended with the transition from commodity-backed monetary systems toward modern fiat money.
Part II picks up from there. Once money became fully centralized and detached from physical scarcity, inflation evolved from an occasional act of debasement into a permanent feature of the monetary system. The question is no longer simply why inflation occurs, but why a system that steadily erodes purchasing power has become so deeply embedded in modern economic and political structures.
I explore why this illusion persists, how control over money and credit concentrates economic and political power, and why remarkably similar mechanisms of monetary control have appeared across very different political systems.
This sets the stage for my next newsletter, where I will turn from inflation to deflation and explore why falling prices driven by productivity should be understood not as economic failure, but as an expression of genuine prosperity.
Best regards,
Leon
PS: For everyone who has already pre-ordered my book—thank you. For those interested, Digital Real Estate is available for pre-order, and you can secure the German edition here. There will also be a special piece of art hidden inside the book. I’ll share more about the artwork and the story behind it in the next newsletter.
DEEP DIVE
Inflation and the Illusion of Wealth Part II
By the twentieth century, money creation had been fully centralized and detached from physical scarcity. What had once been a constraint on power became a tool of policy.
Across monetary history, the structure has remained remarkably consistent. First, money is centralized for convenience or security. Then, claims are issued in excess of reserves. Inflation follows, redistributing wealth toward those closest to monetary issuance. Because there are many short-term winners, the system persists longer than expected—and people forget that it is structurally destined to fail.
Trust erodes, inequality rises, and economic coordination deteriorates. Finally, the system either collapses or is reset under a new standard.
Fiat money is not a historical aberration; it is the latest stage in a long pattern of monetary debasement. What distinguishes the modern system is not the presence of inflation, but its scale and permanence. Earlier societies were limited by the physical costs of debasement—metal had to be mined, coins had to be clipped, notes still had to be printed.
Today, money can be created digitally at virtually no cost, allowing the same dynamics to operate continuously rather than episodically. However, history repeatedly shows that when money becomes an instrument of political discretion rather than a scarce economic good, its ability to function as a stable store of value deteriorates. Inflation follows, wealth concentrates, and the foundations of long-term prosperity are undermined.
Why the Illusion Persists
Rising GDP, higher nominal wages, and booming asset markets are often cited as evidence of economic success. But these metrics measure activity in currency terms, not real value creation. If the unit of measurement is being diluted, apparent growth can mask stagnation or decline. This is why inflation creates the illusion of prosperity:
- Asset prices rise, but affordability falls
- Debt expands, but productive capacity does not keep pace
- Living standards stagnate even as financial markets surge
The economy appears larger, yet individuals find it harder to save, plan, and build lasting security. Inflation endures not because it creates real wealth, but because it is politically convenient.
It allows governments to finance spending without immediate taxation and enables financial systems to operate through continuous credit expansion. Losses are socialized through rising prices, while gains remain concentrated among those closest to monetary issuance.
But this illusion is not merely the result of incentives—it is ideologically reinforced. Modern economic doctrine has been built around the belief that centrally managed money, credit expansion, and “demand stimulation” are necessary for prosperity.
From Marx and Engels’ call in the Communist Manifesto for the “centralisation of credit in the hands of the state, by means of a national bank with State capital and an exclusive monopoly” to Keynesian arguments for managed inflation and government intervention, a common assumption persists: that economic outcomes can be improved by controlling money.
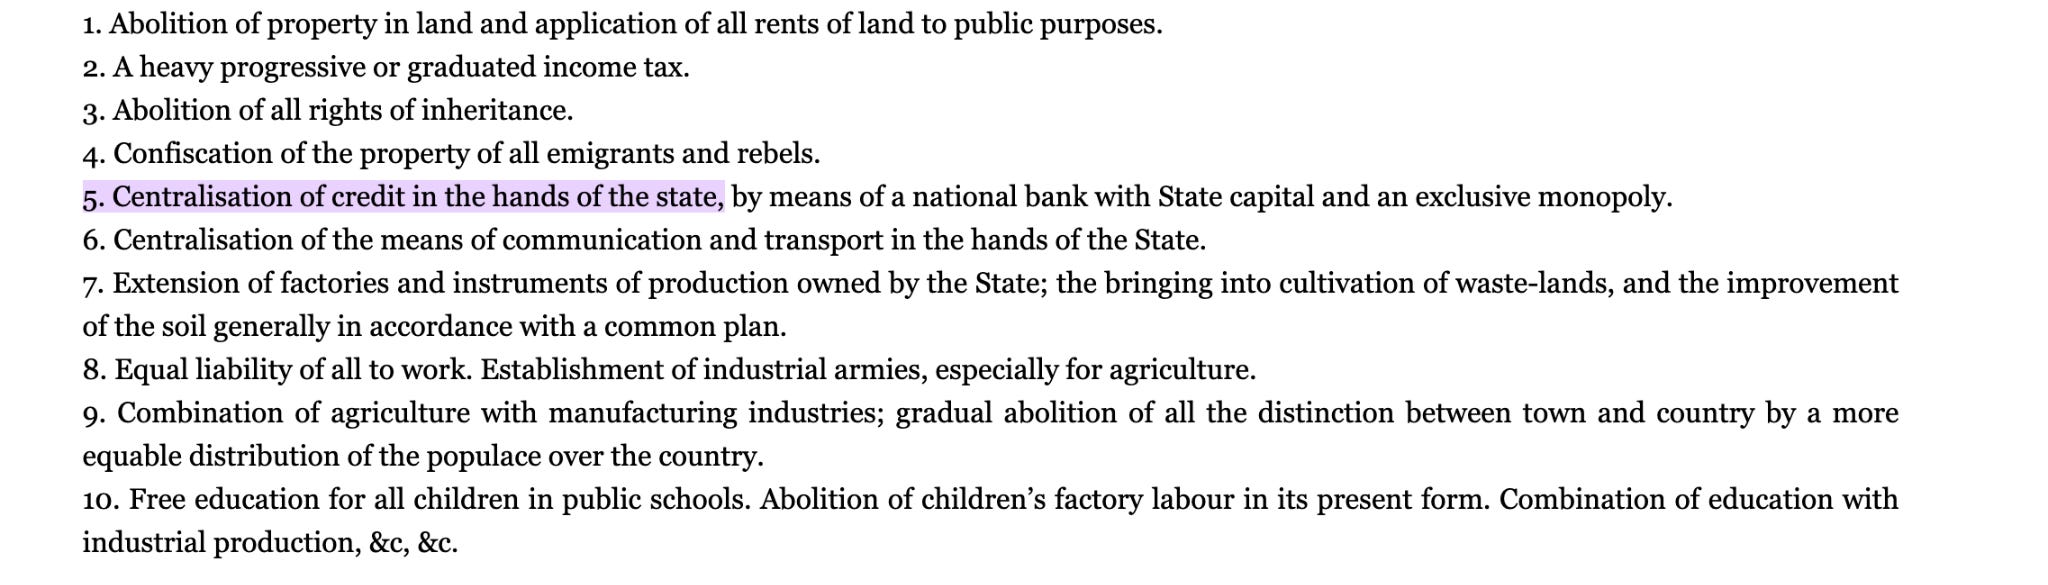
Marx and Engels, The Communist Manifesto (1848), Chapter II. Among the measures proposed is the “centralisation of credit in the hands of the state, by means of a national bank with State capital and an exclusive monopoly.”
There is a historical irony here. The centralization of credit was explicitly presented by Marx and Engels as one of the measures through which the existing economic order could be transformed. Yet centralized monetary institutions have since become a defining feature of economies that describe themselves as liberal, democratic, and market-based.
This does not make modern central banking communist. It does, however, reveal how mechanisms of economic control can transcend political labels. Systems that appear ideologically opposed may nevertheless rely on similar institutional tools: centralized control over money and credit, discretionary intervention, and the concentration of monetary authority.
Following this institutional thread through the twentieth century reveals how mechanisms of monetary control could transcend political ideologies and reappear under very different systems of government. The political language may change, but the underlying human impulse toward control often expresses itself through remarkably similar structures.
John Maynard Keynes, whose ideas came to dominate twentieth-century economic policy, institutionalized this worldview. By rejecting monetary standards such as gold and framing inflation, deficit spending, and central banking as tools of stability and growth, he provided governments with a theoretical justification for permanent monetary intervention.
What was presented as pragmatic economics embedded a political logic into money itself: Prosperity could be engineered from above through credit expansion rather than earned through proof of work, saving, production, and innovation.
This political dimension was not incidental. When The General Theory of Employment, Interest and Money (1936)—the foundation of modern Keynesian economics—was published in Germany under Hitler, Keynes wrote a special preface noting that his framework was “much more easily adapted to the conditions of a totalitarian state than under conditions of free competition and a large degree of laissez-faire”.
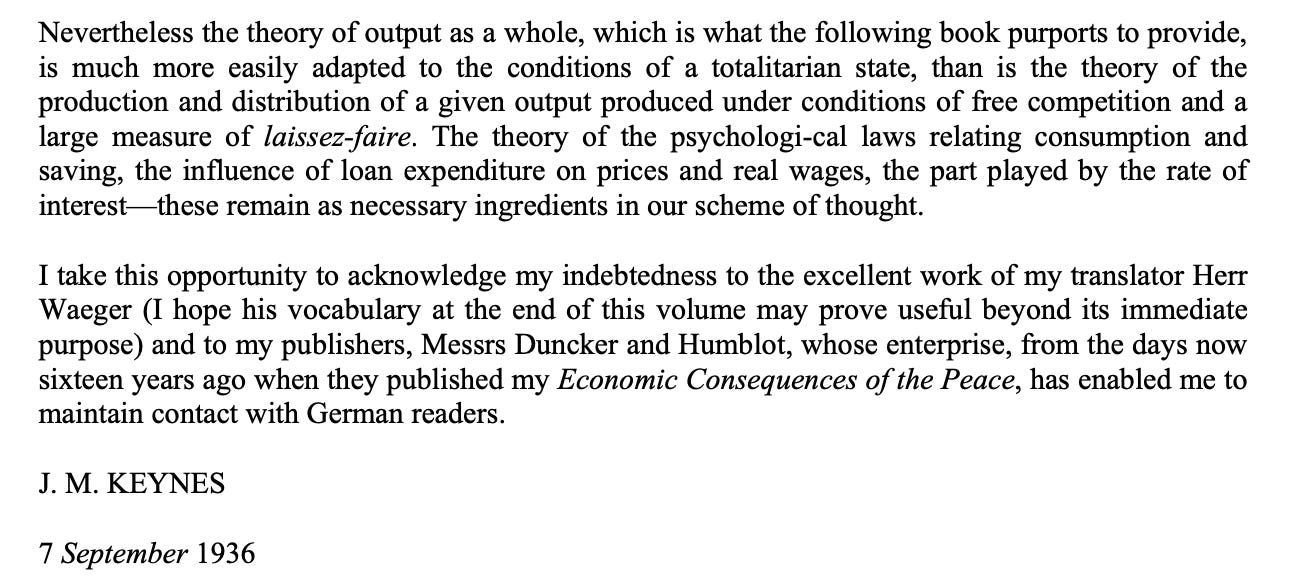
Excerpt from John Maynard Keynes’s preface to the German edition of The General Theory of Employment, Interest and Money, September 7, 1936.
The irony is difficult to ignore. Keynesian economic policy would later become deeply embedded in modern democratic states, including among progressive political movements. Yet Keynes himself acknowledged that his framework for managing aggregate economic activity was more readily adaptable to a totalitarian state than to one characterized by free competition and laissez-faire.
This does not make Keynesian economics inherently authoritarian. But it does reveal a deeper tension: The same instruments that expand the state’s capacity to manage money, credit, and aggregate demand also expand its capacity for economic control. Political labels do not resolve that tension; institutional incentives matter more than the language used to justify them.
The National Socialist regime, which had risen in the aftermath of monetary collapse and hyperinflation of the 1920s, embraced centralized credit, state-directed investment, and monetary manipulation as instruments of economic control. Inflationary finance and credit allocation were used to mobilize industry, subordinate markets, and consolidate political authority.
This continuity was embodied by Hjalmar Schacht, who had served as president of the Reichsbank during the Weimar Republic and was reappointed to the position by Hitler in 1933. Schacht subsequently devised the Mefo-bill system, a form of off-budget credit that enabled the regime to finance and conceal much of its rapid military rearmament.
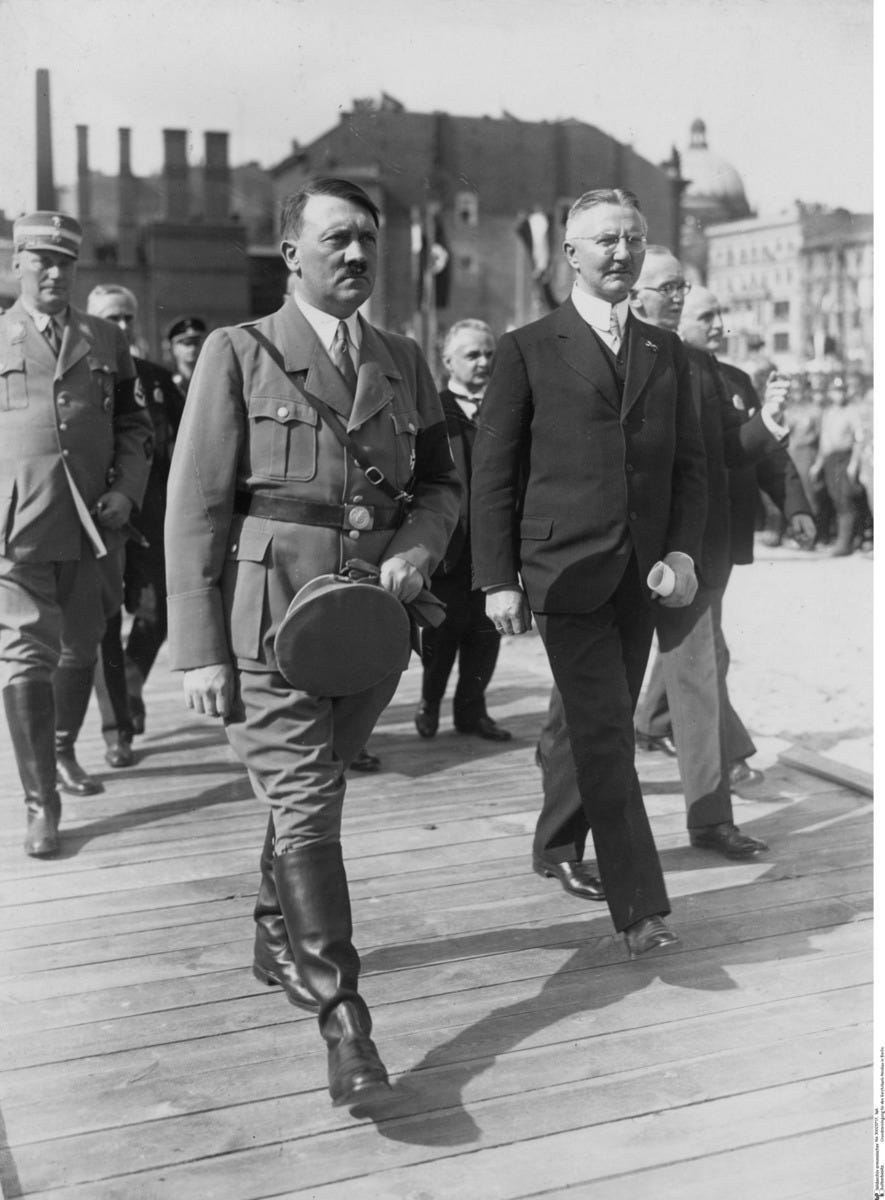
Adolf Hitler with Reichsbank President Hjalmar Schacht, May 5, 1934. Having already served as Reichsbank president during the Weimar Republic, Schacht returned to the position under Hitler in 1933—a striking example of how monetary institutions and their technocrats can persist across radically different political regimes. His subsequent financing mechanisms helped enable the regime’s rapid rearmament. Source: [germanhistorydocs.org]
The lesson is structural: When money becomes an instrument of policy rather than a neutral measure of value, economic and political power necessarily converge. The mechanisms presented as tools of stability do not merely enable authoritarian consolidation—they drive it.
Once money is transformed from a neutral measuring stick into a policy instrument, market coordination gives way to political command, and the concentration of economic power becomes the concentration of political power.
This arrangement did not arise by accident. For much of history, money was not the exclusive domain of the state. Competing issuers and commodity-based standards imposed discipline through scarcity and redemption. Once that competition was removed and monetary control centralized, inflation became structurally embedded.
Over time, the cost becomes systemic: distorted markets, fragile debt structures, declining trust in money, and growing dependence on asset inflation for perceived economic stability.
What begins as apparent stimulus becomes dependency. Inflation persists not because it works, but because it masks failure—substituting monetary expansion for real productivity while maintaining the appearance of growth. The illusion of prosperity exists because the system masks its own cost.
Nowhere is this more visible than in housing. As money loses its function as a store of value, real estate absorbs monetary demand, prices can detach from underlying utility, and shelter becomes increasingly financialized.
This dynamic—and how it might be reversed under a harder monetary standard—will become central as we move from inflation to the natural market forces of productivity and price decline.
Transition to Deflation
If inflation is not the engine of prosperity, but its illusion, then the natural question follows: What drives long-term wealth?
The answer is productivity, innovation, and saving—forces that, under a stable monetary standard, can express themselves through falling prices alongside rising real value. Deflation, viewed through this lens, is not economic failure, but technological progress made visible.
In my next newsletter, I will explore deflation not as a threat, but as the expression of genuine economic growth—and why a system built on perpetual debt must resist it, while a bitcoin-based monetary system can allow productivity gains to flow more directly into purchasing power.
WORTH KNOWING
Podcast and publications
Digital Real Estate — Pre-Order — My book Digital Real Estate is available for pre-order in both English and German. Thank you to everyone who has already pre-ordered a copy. PRE-ORDER
Bitcoin Treasuries Podcast — Dylan LeClair of Metaplanet joins Miller Cole to discuss Japan’s potential Bitcoin inflection point. They explore Metaplanet Securities, the firm’s new Type 1 securities licence, and how it could open access to Japan’s vast pool of household savings. The conversation also covers Project Nova, tokenised dividends, Metaplanet’s preferred instruments, and why the current digital-credit stress test may ultimately strengthen institutional conviction. WATCH
Building the Next Capital Market — Dylan LeClair joins Natalie Brunell to explain why the current sell-off does not change the underlying opportunity. From Metaplanet Securities to perpetual preferreds, the conversation explores how Bitcoin is being integrated into Japan’s capital markets—and why sentiment often lags adoption. WATCH
IDEAS OF INTEREST
Algorithms, Attention, and Incentives — A reflection on how modern algorithms shape beliefs by rewarding novelty, outrage, and emotional engagement. The broader argument is that reclaiming attention—and becoming comfortable with boredom—may be one of the most important forms of resistance in an economy built on capturing human focus. READ
Money Creation Has Outrun Economic Growth — Across the G7, money supply has expanded far faster than nominal output since 2004. In the US, M2 rose 279% versus 171% nominal GDP growth, while refinancing costs now exceed $1 trillion annually. Debt is no longer merely financed by growth; inflation increasingly becomes the mechanism through which nominal promises are maintained. READ
The Bond Market Is Setting the Terms — As US long-term yields push toward post-2007 highs, debt-service costs and refinancing pressure are becoming the central constraint on fiscal policy. At the same time, Washington’s coordinated support for Japan shows that FX, Treasury liquidity and alliance management are increasingly treated as one strategic system. READ
America’s Yen Put — Washington has signalled it may join Japan in buying yen, while the FIMA facility gives Tokyo dollar liquidity against its Treasury holdings. The significance is not merely FX intervention: the US is treating the yen, Japan’s bond market and Treasury-market stability as linked strategic interests. Japan can defend its currency with less pressure to liquidate Treasuries—and Washington protects a crucial pillar of its dollar alliance. READ
When Randomness Fails — The Coldcard flaw is a sobering reminder that self-custody removes counterparty risk, not implementation risk. Bitcoin’s cryptography did not fail; the failure was in the entropy used to create affected wallet seeds, reportedly making them searchable within hours. Independent entropy, wallet audits and robust multisig setups matter long before a transaction is signed. WATCH | READ
The mNAV Recycling Loop — Strategy’s $25M STRC repurchase below par shows how its capital structure can compound in both directions: issue common or preferred equity when it trades at a premium; repurchase it when discounted. Bitcoin is not merely an asset to accumulate—it becomes strategic inventory used to maximise value per common share. READ
If you want to support me, feel free. You can send me some satoshi/bitcoin.
Lightning: law@getalby.com
On-chain: bc1qyc9q89wjzmvaw729tj3wsrsfhft53mjycrjxdk
Nostr PubKey
npub1v5k43t905yz6lpr4crlgq2d99e7ahsehk27eex9mz7s3rhzvmesqum8rd9
Resources
Karl Marx & Friedrich Engels – Manifesto of the Communist Party, Chapter II: Proletarians and Communists (1848) — READ
John Maynard Keynes – The General Theory of Employment, Interest and Money, Preface to the German Edition (1936) — READ
Hjalmar Schacht – The Nazi Regime’s Financial Architect WATCH
Photo Credit: planet-wissen.de
Disclaimer: the content is for informational purposes only, you should not construe any such information or other material as legal, tax, investment, financial, or other advice. Make sure you do your own research before making any investment and be aware of your own risk tolerance.
If you like to build on my thoughts, feel free, but please cite me as the source. 2026 – Leon Wankum.
Editing and content creation by Clemens Haidinger.
0A79 E94F A590 C7C3 3769 3689 ACC0 14EF 663C C80B


