


The Bitcoin Newsletter 39
Welcome to the 39th Edition of The Bitcoin Newsletter
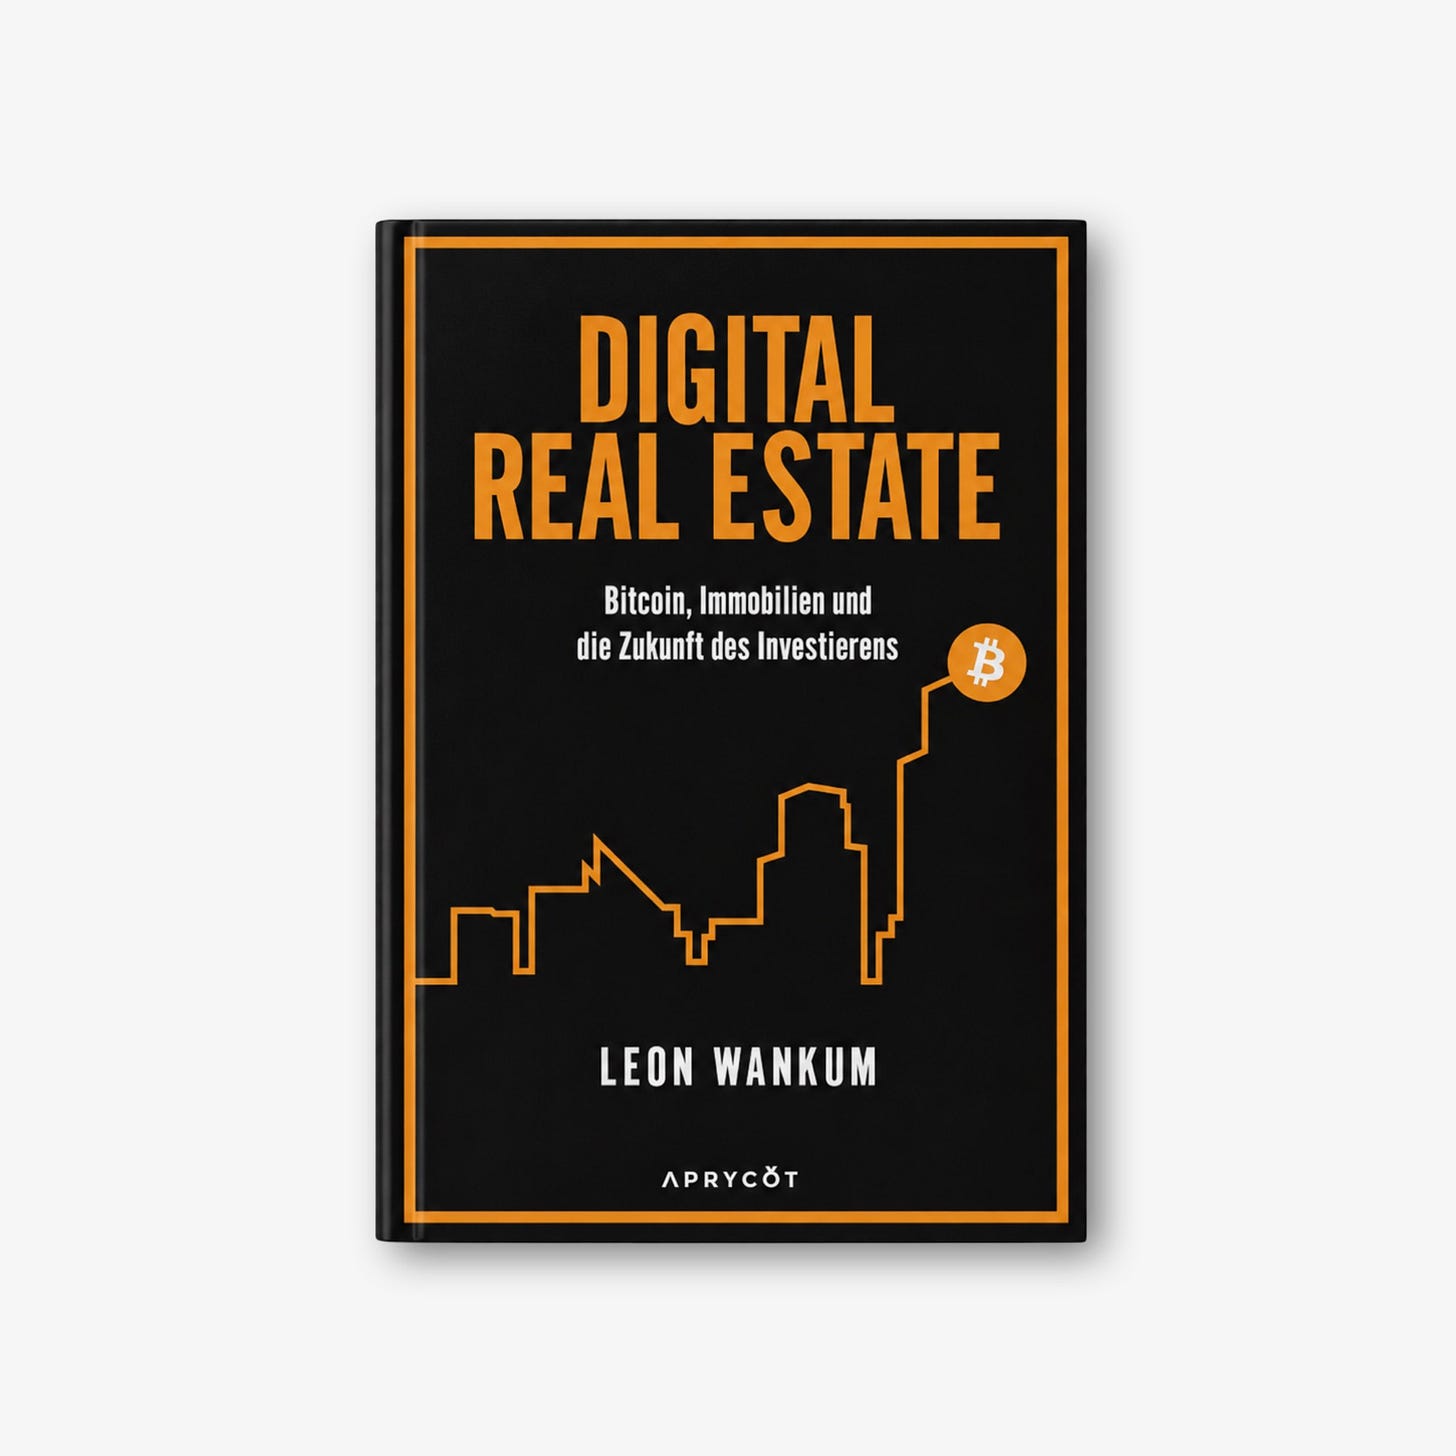
The German edition of my book Digital Real Estate is now available for pre-order through Aprycot Media. This means that the German-speaking Bitcoin community will receive the translated edition in October—just one month after the release of the English version in the US with BTC Media.
I joined Niko Jilch for a live show to officially launch the German pre-order. The response was fantastic, and I’m grateful for the support the book has received so far.
The day after the event, we also recorded several new episodes, which will be released in the coming weeks. These conversations will expand on many of the ideas covered in the book and continue to build out our German Bitcoin Masterclass series.
For everyone who has already pre-ordered the book—thank you. And for those interested in the German edition, you can now secure your copy here.
The English edition is also available for pre-order: Digital Real Estate (ENG)
This week’s newsletter ties directly into one of the central themes explored in Digital Real Estate: the relationship between money, asset prices, and the illusion of wealth.
Real estate sits at the center of this dynamic. As property prices rise alongside monetary inflation, it often appears as though wealth is being created. Yet the opposite is happening. The currency in which assets are measured is losing purchasing power, and rising nominal prices are mistaken for genuine prosperity.
In this two-part series, I explore why the illusion of wealth created by monetary inflation has persisted for so long, the economic and social consequences it produces, and why bitcoin offers a path out of that illusion.
In Part I, I examine how money creation creates the appearance of prosperity, distorts economic signals, concentrates wealth, and follows a pattern that has repeated throughout monetary history.
Best regards,
Leon
DEEP DIVE
Inflation and the Illusion of Wealth Part I
Why Money Creation Appears to Create Prosperity
Monetary inflation is often defended on the grounds that it stimulates economic growth. New money enters the economy through government spending, credit expansion, and financial markets, creating the appearance of rising activity, higher asset prices, and expanding wealth.
In the short term, this can feel like prosperity: Consumption increases, borrowing becomes easier, and nominal incomes rise. But this effect is deceptive. Money creation does not increase the economy’s productive capacity.
It does not create more real value. It merely redistributes purchasing power. Those who receive newly created money first can spend it before prices adjust, while those who receive it later face higher prices without corresponding income increases.
What looks like growth is, in reality, a reallocation of existing value. What appears as prosperity is not the result of greater efficiency or genuine value creation, but of monetary manipulation that temporarily rearranges purchasing power.
The system feels prosperous precisely because it conceals its own cost. Nowhere is this more visible than in housing. Unlike many consumer goods, real estate absorbs monetary demand in addition to serving a productive function.
As the money supply expands, a significant portion of newly created purchasing power flows into property markets, pushing prices higher.
As a result, housing prices often rise alongside monetary inflation, creating the impression that homeowners are becoming wealthier when much of the increase merely reflects the declining purchasing power of the currency itself.
How Inflation Distorts Economic Signals
In a functioning market, prices convey information about scarcity, demand, and opportunity cost. Monetary inflation disrupts this signaling system. When prices rise because more money is entering the system—not because goods are becoming scarcer or better—economic actors cannot distinguish between real growth and monetary distortion.
This has several consequences:
- Malinvestment: Capital flows into projects that appear profitable only because of cheap credit, not because they meet genuine demand.
- Asset Inflation: Stocks, bonds, and especially real estate rise in price, not due to increased productivity, but because excess money seeks a store of value. Real estate absorbs a particularly large share because it is scarce, tangible, income-producing, and easily financed, while its supply cannot expand as quickly as money and credit.
- Shortened Time Horizons: When money loses value over time, consumption and unnecessary speculation are rewarded over patience and long-term planning.
Inflation thus reshapes behavior. Instead of encouraging productive investment and capital formation, it systematically incentivizes artificial financial engineering, leverage, and speculative positioning over genuine value creation.
Why Inflation Concentrates Wealth
Inflation systematically benefits some at the expense of others. Governments, banks, and large financial institutions receive newly created money first. They acquire assets before prices adjust. By the time this money reaches wages and consumer goods, much of its purchasing power has already declined. This is known as the Cantillon Effect.
Access to this new money is itself shaped by existing wealth. Those with stable incomes, strong credit profiles, and assets to pledge as collateral can borrow more easily and use that credit to acquire further assets.
As inflation lifts nominal asset prices and erodes the real burden of fixed debt, their wealth and borrowing capacity increase. More assets create greater access to credit; greater access to credit enables the acquisition of more assets. The advantage compounds.
This is not a neutral process; it is a transfer of wealth. Even a “moderate” inflation rate of 2% halves a currency’s purchasing power in roughly thirty-five years. What appears as stability in any single year becomes confiscation across a lifetime.
Savings lose value, wages lag behind asset prices, and those without access to early credit are systematically disadvantaged.
Inflation therefore functions as a form of invisible taxation—one that requires no legislation, no public vote, and no transparency—and which, in its effect, amounts to a legalized form of wealth confiscation.
It redistributes wealth away from savers and wage earners toward the issuers and early recipients of money. In this sense, inflation is not merely a technical policy tool; it is a structural mechanism of expropriation.
In practical terms, this means:
- Savers lose purchasing power.
- Wage earners fall behind asset holders.
- Those closest to monetary issuance gain a disproportionate advantage.
Over time, this dynamic concentrates wealth, widens inequality, and entrenches financial power—while remaining politically easier than direct taxation.
Historical Patterns of Monetary Debasement
The dynamics described above are not unique to modern fiat systems. Throughout the world’s known history, whenever money has been detached from scarcity and placed under centralized control, the same pattern has reappeared: monetary expansion, redistribution toward those closest to issuance, rising inequality, and eventual loss of trust.
Warnings against monetary manipulation are among the oldest in economic thought. Aristotle criticized the debasement of coinage as an abuse of political power. In ancient India, the Arthashastra, a Sanskrit treatise on statecraft, politics, and economics, cautioned rulers against reducing the metal content of money, recognizing the damage such practices caused to trade and taxation.
In China, early experiments with paper money collapsed once issuance exceeded reserves, triggering inflation and social instability. In Europe, Nicolaus Copernicus articulated the quantity theory of money in the sixteenth century, observing that excessive issuance inevitably debases currency.
Across civilizations, the principle was understood: When money can be created without cost or constraint, its value erodes. Historical evidence that inflationary systems are ultimately unsustainable is abundant.
From Imperial Rome, where repeated debasement of the silver coin denarius and later the gold coin solidus fueled economic breakdown, to the Byzantine Empire, where monetary dilution accelerated political and fiscal decline, the pattern is clear.
In seventeenth-century Sweden, Johan Palmstruch’s Stockholms Banco overissued banknotes, triggering a financial collapse; rather than abolishing the practice, the state absorbed it and institutionalizing fractional-reserve banking. Laying the foundations of modern central banking by establishing Sweden’s central bank, Sveriges Riksbank, on September 17, 1668.
The nineteenth-century gold standard temporarily restored monetary discipline by anchoring currencies to scarce reserves. Yet its constraints soon proved politically inconvenient. Wars, economic crises, welfare commitments, and expanding bureaucracies required spending beyond what governments could raise through taxation or genuine savings without provoking resistance.
Monetary expansion offered a less visible alternative: it allowed expenditure to be brought forward, shifted part of the cost onto currency holders, and reduced the real burden of fixed-rate public debt. Redemption requirements were therefore repeatedly suspended, weakened, and ultimately abandoned, completing the transition to fiat money.
In Part II, I will examine why the inflationary system persists despite its long-term costs, how housing became increasingly financialized, and why deflation—rather than inflation—is the natural expression of productivity and economic progress.
Finally, I show why bitcoin offers an alternative to the perpetual cycle of monetary expansion that has plagued humanity throughout history.
WORTH KNOWING
Podcast and publications
German Pre-Order: Digital Real Estate 🇩🇪 — The German edition of Digital Real Estate is now available for pre-order through Aprycot Media and is expected to be released in October, just one month after the English edition. The book explores bitcoin’s rise as a store of value, its implications for real estate, and how entrepreneurs, investors, and businesses can integrate bitcoin into balance sheets, capital allocation, and long-term strategy. PRE-ORDER
Niko Jilch Live Show 🇩🇪 — It was a pleasure joining Niko Jilch for a live show in Vienna, the home of the Austrian School of Economics, to officially launch the German pre-order of Digital Real Estate. We discussed inflation, the illusion of wealth, monetary self-determination, bitcoin, and many of the core ideas explored in the book. We also recorded several new episodes for our Bitcoin Masterclass series, which will be released on Niko’s YouTube channel in the coming weeks. WATCH
IDEAS OF INTEREST
El Bademantel Ambassador — The Fabian Society and the Strategy of Gradualism 🇩🇪
German Bitcoiner “El Ambassador” has launched a German-language series on the history and influence of the Fabian Society, a British socialist movement that advocated gradual rather than revolutionary social change. The series examines how Fabian ideas have influenced universities, political parties, public institutions, and modern Western society over the past century. It is a fascinating deep dive into the intellectual origins of many ideas that the author argues are rooted in socialist and Marxist thought, despite often being presented as liberal, progressive, or mainstream. READ
Strategy’s STRC Stress Test — Joe Burnett breaks down why STRC trading below $80 should be viewed less as a solvency event and more as a leverage flush among overextended speculators. The discussion explains how Strategy’s preferred stock works, why trading below par does not automatically imply distress, and why Bitcoin-backed credit may become an important test case for yield-seeking capital markets. WATCH
Strategy’s Digital Credit Framework — Adam Livingston breaks down why Strategy’s new announcement should be viewed less as panic management and more as a shift toward active Bitcoin-backed capital allocation. The discussion explains how the $1.15B USD reserve raise, STRC dividend increase, buyback authorizations, and limited BTC monetization give Strategy more levers to defend its credit stack while preserving long-term Bitcoin exposure. WATCH
Dylan LeClair BFC Keynote — Dylan LeClair shares his latest views on the bitcoin market cycle, why the current bear market is laying the foundation for the next bull run, and Metaplanet’s long-term strategy to accelerate bitcoin adoption in Japan and beyond. WATCH
The Fed Is Trapped — Lawrence Lepard breaks down why the Fed’s retreat from forward guidance should be viewed less as discipline and more as cover for future rate cuts and money creation. The discussion explains why sovereign debt, fragile bond markets, and persistent deficits make genuinely tight policy unsustainable — and why Lepard believes the next phase could bring double-digit inflation, stronger hard assets, and a renewed case for Bitcoin. WATCH
Metaplanet: From Bitcoin Treasury to Financial Platform — Metaplanet is acquiring regulated broker Siiibo Securities for approximately $13.1 million, adding the licenses and distribution capabilities required to develop Bitcoin-linked bonds and tokenized securities. The acquisition marks its evolution from holding Bitcoin as a treasury asset to building a broader Bitcoin-centric financial ecosystem in Japan. READ
Bitcoin Treasuries: The Coupon Challenge — Perpetual preferred equity removes maturity risk, but not the cost of its recurring coupon. The real advantage belongs to companies that can fund these payments through operating income rather than issuing shares or selling Bitcoin. An interesting perspective on how the Bitcoin treasury model could evolve further. READ
If you want to support me, feel free. You can send me some satoshi/bitcoin.
Lightning: law@getalby.com
On-chain: bc1qyc9q89wjzmvaw729tj3wsrsfhft53mjycrjxdk
Nostr PubKey
npub1v5k43t905yz6lpr4crlgq2d99e7ahsehk27eex9mz7s3rhzvmesqum8rd9
Resources
Niko Jilch – Bitcoin Masterclass mit Leon Wankum WATCH
Leon Wankum – Bitcoin and Real Estate READ
Leon Wankum – Real estate vs. Bitcoin: Dismantling The Cash-Flow Narrative READ
Sveriges Riksbank – Money and power: The history of Sveriges Riksbank READ
Photo Credit: “Hyperinflation in the Weimar Republic, 1923.” Public domain via Wikimedia Commons.”
Disclaimer: the content is for informational purposes only, you should not construe any such information or other material as legal, tax, investment, financial, or other advice. Make sure you do your own research before making any investment and be aware of your own risk tolerance.
If you like to build on my thoughts, feel free, but please cite me as the source. 2026 – Leon Wankum.
Editing and content creation by Clemens Haidinger.
0A79 E94F A590 C7C3 3769 3689 ACC0 14EF 663C C80B


