


The Bitcoin Newsletter 42
Welcome to the 42nd Edition of The Bitcoin Newsletter
This is a particularly special edition for me because, after more than three years of researching, writing, rewriting, and refining, Digital Real Estate is finally out.
What a journey, and at times a struggle, it has been to bring this book to life. It still feels somewhat surreal to finally see it released. Thank you to everyone who supported me along the way and to everyone who has already ordered a copy.
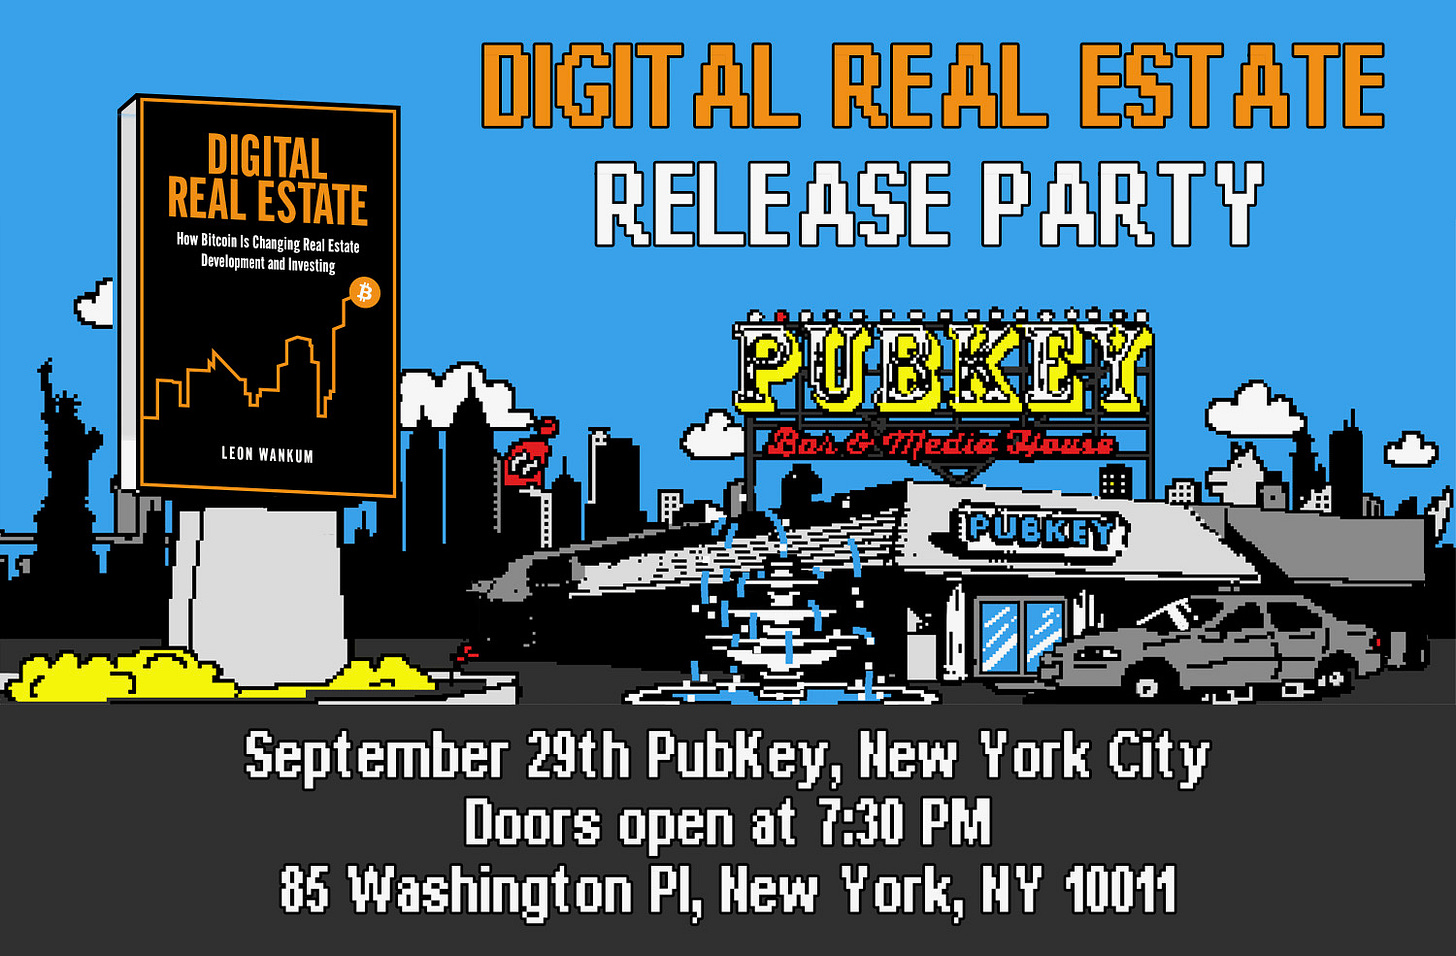
The book is now also available on Amazon for international shipping, and on September 29 at 7:30 PM, we’ll celebrate its release at PubKey in New York. I’m looking forward to bringing the book and its thesis out into the world and discussing these ideas in person.
The timing also fits particularly well with this edition of the newsletter.
Over the past three editions, I have explored the relationship between inflation, deflation, productivity, and monetary systems. [Part I] examined how monetary inflation creates the illusion of prosperity. [Part II] explored why inflation has become a structural feature of our debt-based monetary system. In [Part III], I turned to productivity-driven deflation and why falling prices can represent genuine economic progress rather than economic decline.
This leads to the final question of the series: What kind of monetary system can allow these deflationary forces to operate without destabilizing the financial system?
In Part IV, Bitcoin as the Resolution, I explore how bitcoin’s fixed supply, divisibility, and verifiable scarcity could provide such a monetary foundation, how a bitcoin standard could emerge gradually, and what this could mean for technological progress, savings, and ultimately real estate.
These ideas are also at the heart of Digital Real Estate, making this a fitting Deep Dive for the week of its release.
I hope you enjoy this edition.
Best regards, Leon
DEEP DIVE
Bitcoin as the Resolution
Bitcoin introduces a monetary structure in which neither artificial inflation nor debt-induced deflation is structurally required. Its fixed supply prevents dilution, while its divisibility and global liquidity allow it to function across a wide range of price levels. Crucially, bitcoin’s absolute scarcity does not constrain economic activity, because its divisibility allows prices to adjust downward as productivity rises.
Since new issuance is tied to real resource expenditure through proof-of-work, errors cannot be concealed through monetary expansion; they must be recognized and corrected through market adjustment.
Bitcoin was designed as money. Its monetary properties position it not merely as an investment, but as an emerging form of monetary infrastructure.
A monetary standard is the reference point an economy uses to anchor value: the base asset against which prices, savings, and balance sheets are ultimately measured, even when day-to-day transactions rely on other instruments. In practice, a standard is therefore less about what people spend and more about what individuals and institutions rely on to preserve and measure value.
Importantly, such a standard cannot simply be forced into existence. Monetary standards can be established through law, but they can also emerge organically as market participants converge on an asset that best performs money’s core functions.
Bitcoin follows this latter path: adoption occurs voluntarily and at different speeds across individuals, companies, institutions, and markets. An asset may first be accumulated as a store of value, later become more widely used as a medium of exchange, and eventually serve as a unit of account. A bitcoin standard, if it emerges, is therefore unlikely to arrive everywhere at once. Different monetary systems may coexist for extended periods as adoption unfolds across markets and jurisdictions at different times.
This architecture becomes especially relevant in the context of accelerating technological change. Artificial intelligence, automation, and digital replication are rapidly reducing the economic scarcity of both physical and cognitive labor. As the cost of production falls and the marginal cost of many goods approaches zero, traditional pricing mechanisms anchored in labor or monetary expansion become increasingly unreliable.
In such a landscape, only assets with verifiable and incorruptible absolute scarcity can function as reliable stores of value. Bitcoin provides this base layer. It allows productivity gains to translate into falling prices without triggering systemic collapse, and it enables savings to compound in real terms rather than being eroded by monetary policy.
The implications for real estate are structural. Under fiat, property has absorbed monetary demand as a hedge against debasement, driving prices far above their utility value. Housing has become both a financial asset and a store of value, distorting affordability and capital allocation. In a bitcoin-based system, this monetary premium is no longer necessary. As savings migrate into a superior store of value, real estate can return to its primary function: providing shelter, workspace, and productive infrastructure.
In such an environment, technological progress in construction, modular design, automation, and new materials, can exert its natural deflationary force on housing costs. Developers would need to compete through efficiency and quality rather than through speculative appreciation. Capital would be allocated toward innovation rather than inflation hedging.
As a result, property prices would more closely reflect utility, location, and demand rather than monetary distortion. A bitcoin-backed economy makes it structurally possible, though not automatic, for technological progress to result in lower prices.
This does not imply uniform price declines across all sectors, nor does it eliminate cyclical fluctuations. Prices will still respond to supply, demand, and external shocks. But under a hard-money standard, deflation becomes a signal of progress rather than a trigger for a crisis. Bitcoin therefore does not promise abundance by decree. It removes the monetary distortions that prevent technological abundance from reaching society.
By anchoring money in verifiable absolute scarcity, bitcoin allows productivity, innovation, and efficiency to express themselves directly in lower prices, rising purchasing power, and a more stable foundation for long-term economic coordination.
Bitcoin’s absolute scarcity can help reshape housing and construction practices, fostering greater affordability. This may prove to be one of the most significant socioeconomic consequences of bitcoin’s monetization, as adequate housing is a cornerstone of long-term prosperity.
Going forward, I will explore the broader structural effects of inflation. This is especially consequential for housing, where monetary demand has transformed real estate from primarily a place to live and produce into a financial asset and hedge against currency debasement. Understanding this distortion is essential to understanding how bitcoin could reshape the role and valuation of real estate over time.
WORTH KNOWING
Podcast and publications
Digital Real Estate — Release Party — Digital Real Estate is now available on Amazon for international shipping. On September 29 at 7:30 PM, we’ll celebrate its release at PubKey in New York City. I’m looking forward to bringing the book and its thesis out into the world and discussing these ideas in person. RELEASE PARTY: September 29 | Doors open 7:30 PM | PubKey NYC
Digital Real Estate with Ben Schmidt — Ben and I discuss the core thesis of Digital Real Estate, including why bitcoin can function as property, capital, and collateral alongside real estate. This is the first episode of a new 12-part series in which we’ll dive deeper into the ideas behind the book and the Digital Real Estate thesis. WATCH
Bitcoin, Real Estate, and the Bitcoin Treasuries Conference — I joined Nolan for a live conversation about Digital Real Estate, the relationship between bitcoin and real estate, and some of the ideas I’ll be discussing alongside Grant Cardone at the Bitcoin Treasuries Conference in New York. WATCH
Bitcoin Is Coming For A $500 Trillion Market — In my conversation with Tyler Rowe, we discuss the multidimensional hyperbitcoinization and demonetization of real estate through the adoption of financial products built on top of bitcoin. I’ll also be at the Bitcoin Treasuries Conference in New York on September 28, where I’ll be bringing and discussing my book, Digital Real Estate. WATCH
🇩🇪 Bitcoin Master Series with Niko Jilch — Niko and I continue our series with three new conversations exploring inflation, Bitcoin, real estate, and the transformation of the monetary system. The videos are in German, but can be translated into English using YouTube’s AI dubbing feature.
🇩🇪Everything Is Breaking Now – Except Bitcoin — In the first episode, we discuss the consequences of inflation, the illusion of prosperity it creates, why monetary debasement has accompanied humanity for thousands of years, and how bitcoin could provide an alternative as the existing fiat system comes under increasing pressure. WATCH
🇩🇪Why States Love Real Estate and Fear Bitcoin — In the second episode, we discuss why bitcoin is increasingly competing with real estate as a store of value, how developers can integrate bitcoin into their balance sheets, and why demographics, debt, and changing monetary conditions could fundamentally reshape the real estate market. WATCH | WATCH THE FULL MASTER SERIES
🇩🇪 Bitcoin’s Silent Takeover — How Bitcoin Is Gradually Integrating into the Global Financial System — In this conversation with Philipp Mattheis, we discuss bitcoin’s gradual integration into the global financial system, why governments and debt-based monetary systems fear deflation, and how bitcoin could reshape money, real estate, and the broader financial system. READ
IDEAS OF INTEREST
Money Is for Strangers — Rahim Taghizadegan offers a critical but sympathetic assessment of Bitcoin culture, arguing that bitcoin’s potential lies not in closed circular economies, tribal identity, or “number go up,” but in functioning as neutral money between strangers across borders and time. He calls for less self-congratulation and missionary zeal, and more focus on entrepreneurship, capital formation, productivity, and building things of lasting economic value. READ
Germany’s Energy Policy and the Cost of Intervention — A critique of Germany’s energy policy, contrasting the relatively low long-term cost of Finland’s nuclear waste storage with Germany’s extensive electricity subsidies following its nuclear phaseout. The piece argues that government intervention in energy markets distorts prices, weakens economic resilience, and ultimately shifts the costs of political decisions onto citizens. READ
George Soros and the Open Society Foundations – The Capillary System — An examination of how the Open Society Foundations and related organizations use grants, advocacy, research, legal work, media, and cultural institutions to advance policy goals across multiple levels of society. The piece argues that this decentralized funding network allows ideas and influence to spread from major international institutions down to local politics and civil society. READ
The Housing Paradox — Too few homes, yet “affordable” units sit empty because people cannot afford them. When building and financing costs push required rents beyond household incomes, scarcity and vacancy can exist at the same time. More supply alone cannot solve a problem when the cost of producing that supply is already too high. READ
Inflation Is a Relatively New Phenomenon — From 1800 to 1940, U.S. prices rose just 28% in total. Since 1940, they have risen more than 2,200%. A striking reminder that persistent inflation is not inevitable, but a feature of our modern monetary system—and why preserving purchasing power has become a central challenge for long-term investors. READ
The Peter McCormack Show: The Biggest Fraud in Human History — Professor Richard Werner argues that economic growth depends less on interest rates than on where newly created bank credit flows. His case: decentralized banking that funds productive small businesses can drive investment and growth, while credit flowing into financial assets fuels asset inflation and boom-bust cycles. A provocative discussion on how banks create money, the power of central banks, and why the structure of the banking system matters. LISTEN
If you wish to support my work on The Bitcoin Newsletter, feel free to contribute. You have the option to send some satoshis/bitcoin. Your support is greatly appreciated!
Lightning: law@getalby.com
On-chain: bc1qyc9q89wjzmvaw729tj3wsrsfhft53mjycrjxdk
Nostr PubKey
npub1v5k43t905yz6lpr4crlgq2d99e7ahsehk27eex9mz7s3rhzvmesqum8rd9
Resources
Satoshi Nakamoto — Bitcoin: A Peer-to-Peer Electronic Cash System READ
Satoshi Nakamoto — How divisible are bitcoins and other market/economic questions READ
Leon Wankum – Digital Real Estate BUY
Photo Credit: Seen on Bram Kanstein’s X
Disclaimer: the content is for informational purposes only, you should not construe any such information or other material as legal, tax, investment, financial, or other advice. Make sure you do your own research before making any investment and be aware of your own risk tolerance.
If you like to build on my thoughts, feel free, but please cite me as the source. 2026 – Leon Wankum.
Editing and content creation by Clemens Haidinger.
0A79 E94F A590 C7C3 3769 3689 ACC0 14EF 663C C80B


